
Where the problem starts
Young people in Mexico face tight cash flow and patchy credit histories; gig work and irregular pay can turn small gaps into high-cost borrowing. That reality is why tools like didi finanzas have grown quickly: they offer short-term lending and revolving credit lines that feel immediate but carry interest rate and repayment obligations. The practical aim here is to show how to use those tools without falling into recurring debt.
Common pain points for borrowers
Many borrowers default because of unclear repayment schedules, variable APRs, or overlapping credit limits across apps. Informal workers in Mexico City—especially after the 2020 COVID-19 downturn—saw sudden income shocks that exposed weak emergency savings and limited access to traditional banking. That real-world anchor explains why accessible fintech credit is tempting and why discipline matters.
How these fintech loans typically work
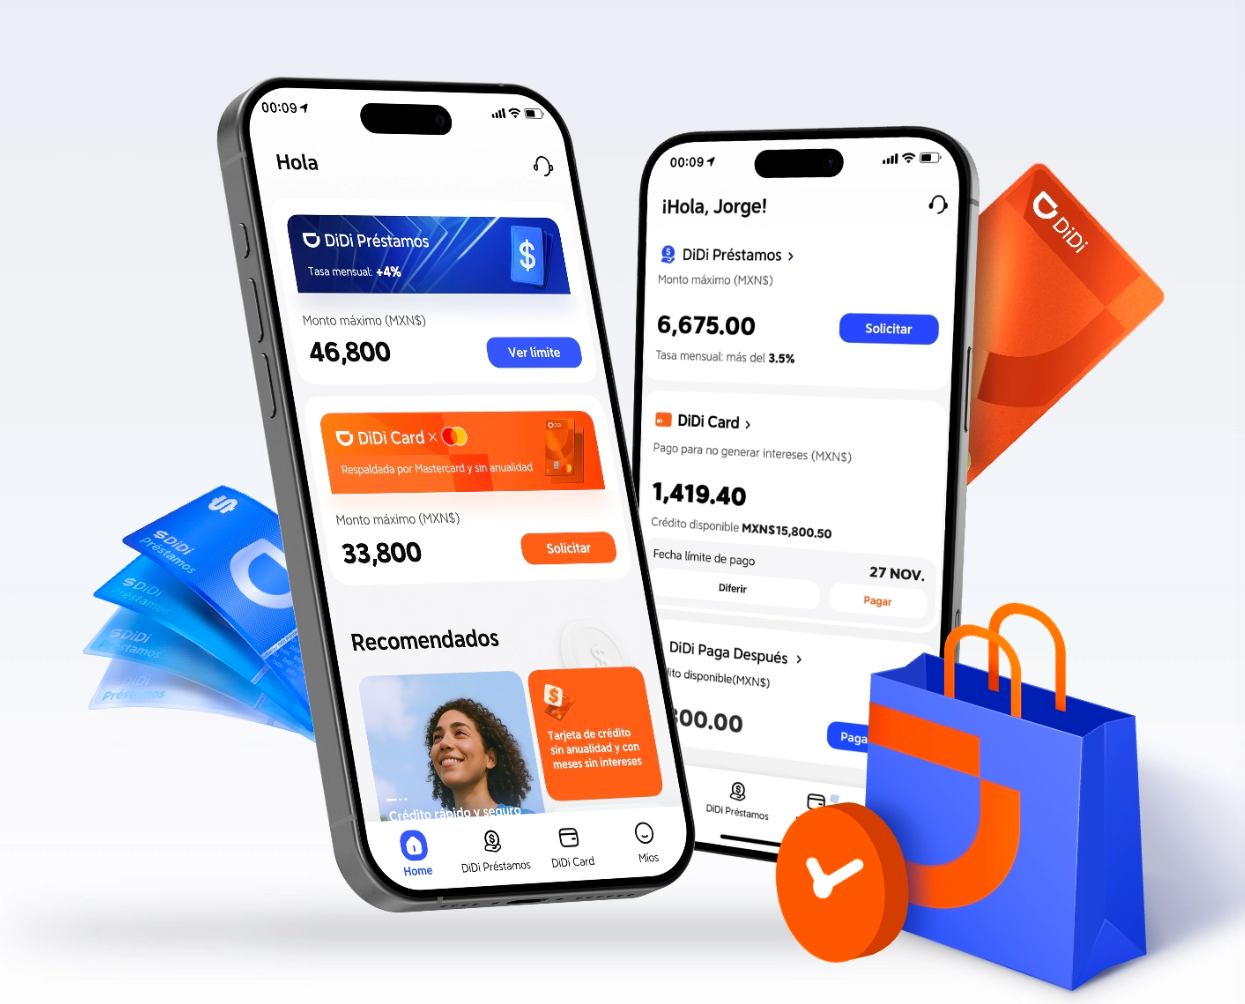
DiDi-style products usually come in two forms: short installment loans and revolving credit lines. Installment loans have fixed repayment dates and a clear interest rate. Revolving credit lets you borrow up to a credit limit repeatedly as you repay—convenient, but risky if you treat it like free cash. Use the app features in didi finanzas app to check balances, due dates, and the effective APR before accepting any offer.
Practical habits to prevent debt slips
Start with three routines that work together: track, prioritize, and automate. Track every loan’s APR and due date in one place. Prioritize high-cost debt first. Automate minimum payments to avoid fees and hits to your credit history. Maintain an emergency buffer equal to at least one month of essential expenses—small, but it stops knee-jerk borrowing. —This buffer is the single most stabilizing habit I see in young clients.
Common mistakes and how to avoid them
Avoid layering multiple revolving lines at once; juggling several due dates breeds missed payments. Don’t ignore the fine print on origination fees and late penalties. Resist the lure of increasing your credit limit as a sign of success—higher credit limits can lead to complacency and faster debt accumulation. Use rules of thumb: never borrow for recurring expenses, and keep total monthly debt service under 30% of take-home pay.
Quick comparison: when to choose an installment loan versus revolving credit
Installment loan: choose for predictable expenses like an appliance repair or a medical bill. You get a set repayment schedule and clearer cost forecasting. Revolving credit: choose only for short-term liquidity with strict discipline—ideal for a one-off shortfall that you can clear within the billing cycle. Track the effective interest rate and the transaction fees; those two numbers determine the true cost more than the headline rate.
Checklist: before you tap “accept”
– Confirm the repayment schedule and mark the first three due dates in your calendar. – Calculate total cost (principal + fees + interest) and compare to an alternative (family loan, savings). – Ensure automated payment is possible through the app and won’t overdraft your account.
Three golden rules for choosing tools and strategies
1) Cost clarity: pick products that show APR and total repayment upfront. 2) Repayment fit: the payment frequency should match your cash flow cycle (weekly vs. monthly). 3) Recovery path: choose lenders with clear hardship options and transparent customer support.
Closing thought
Follow those rules and you’ll limit surprise fees and build a reliable credit record—small measurable wins that compound. DiDi Finanzas fits as a practical option when used with discipline and the checklist above. —Solid habits beat quick fixes every time.