
Quick read and the setup
This one cuts straight: the fintech play in Mexico is different now, and DiDi moved into finance with texture and tempo. Right away, check the product side at didi finanzas — their pitch mixes driver payouts, credit features and card-style perks. The Comparative Insight here is simple: we line up DiDi Finanzas against banks and other fintechs, focus on real costs like transaction fee, APR and cashback value, and give practical checks you can use today.
How DiDi Finanzas functions in plain terms
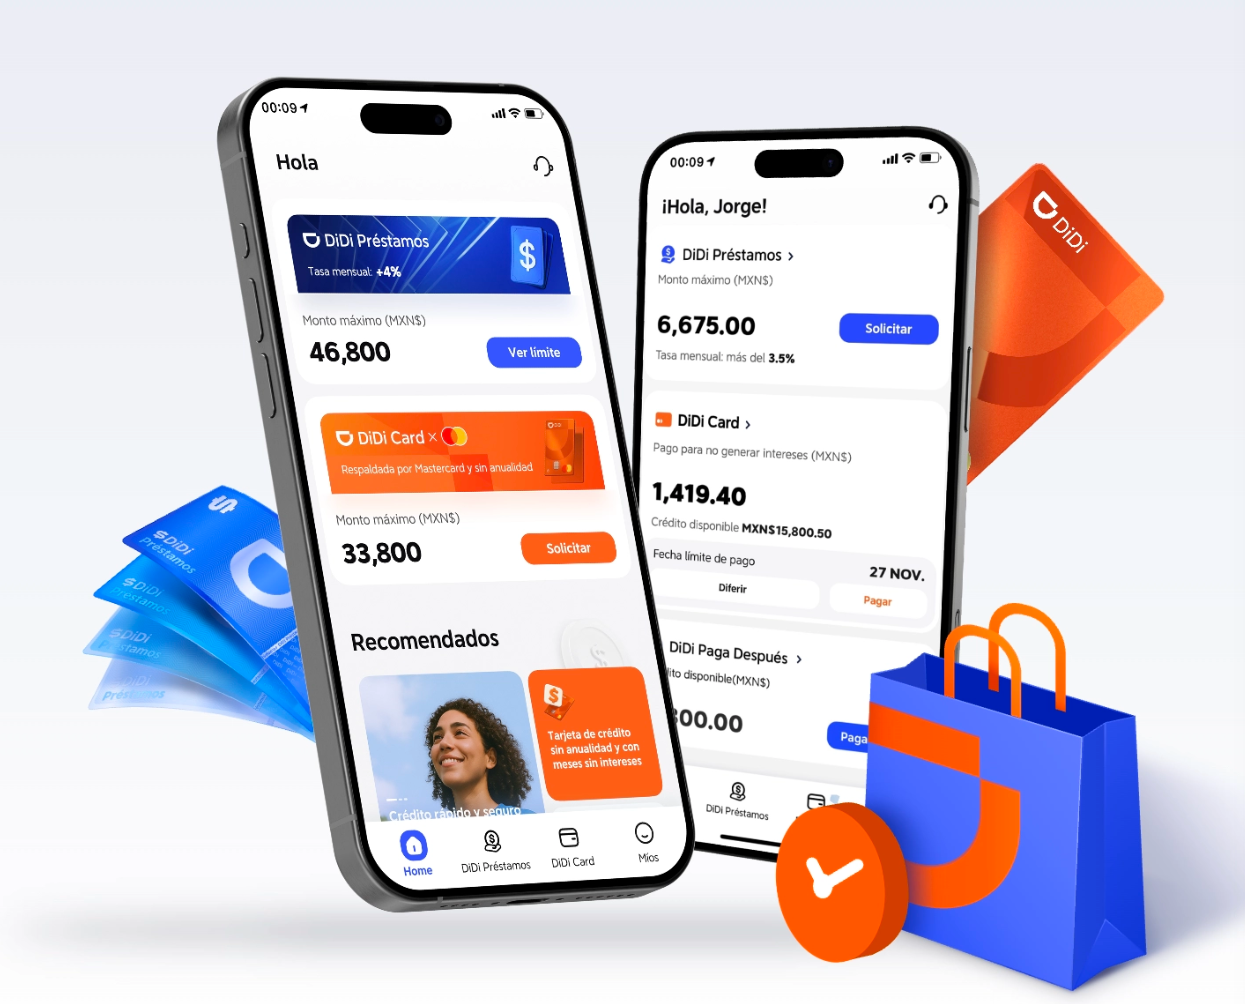
DiDi Finanzas combines digital wallet features, credit options and a cashback model tied to card spending and platform transactions. User onboarding aims for speed, with mobile-first account setup and basic KYC. For many riders and drivers in Mexico City, that mobile-first path reduces friction compared with branch-bound banks. If you want the app perspective, explore the didi finanzas app for interface notes and available services.
Fees, interest and cashback — side-by-side
Look at three measurable pillars: fees, interest rate and cashback yield. Traditional banks often charge monthly maintenance, merchant fees and strict APR tiers on credit. DiDi Finanzas tends to trade some fixed fees for variable charges tied to transactions and service use. Cashback is the headline: the real value depends on effective yield after fees, not the headline percentage. Measure cashback as net return after transaction fee and any minimum spend. Also watch loan origination or advance charges on credit — they eat at apparent savings.
Where DiDi shines and where it dips
Strengths: convenience, targeted cashback for platform users, and slick mobile payments that sync with ride flow. Weak spots: coverage limits, selective eligibility for credit offers, and transparency gaps when small fees appear on statements. In practice, a driver in Guadalajara reported faster claim turnarounds for earnings but noted small payout fees over time — those little bits add up on monthly statements. That real-world anchor—local user reports from major Mexican cities—matters more than marketing lines.
Common mistakes people make — avoid them
First, treating cashback as pure profit rather than net return after fees. Second, skipping the fine print on interest calculation and compounding. Third, using short-term advances repeatedly instead of addressing cashflow — that raises effective APR quickly. Watch for hidden transaction fee lines during refunds and reversals — they can surprise you. Be mindful of credit score impact when you accept multiple small advances. Small oversight now becomes habit later — and costly.
Alternatives and a practical checklist
Compare DiDi Finanzas with: established retail banks (broader branch services, predictable fee schedules) and standalone fintech cards (higher cashback categories but tighter onboarding). Use this checklist before you commit:- Confirm the exact APR or interest rate and whether it’s fixed or variable.- Calculate net cashback: gross cashback minus any transaction or monthly fees.- Check limits on cashouts and timing for payouts to avoid liquidity gaps.- Review dispute and refund policies for merchant charges.Follow those items and you’ll see where real value sits.
Advisory close — three golden rules
1) Evaluate net return, not headline rates: always subtract fees to understand true cashback yield. 2) Prioritise flexibility: pick services with clear payout timelines and transparent fee schedules to protect day-to-day cashflow. 3) Monitor credit impact: frequent short-term credit can damage credit score and raise cost of capital. These metrics let you compare DiDi Finanzas against banks and fintech peers with numbers, not promises. DiDi Finanzas fits when you need integrated ride-to-wallet convenience and measured cashback — and it becomes the sensible tool when those three rules are met — dash-led thinking helps keep choices grounded.